

How modern QM technologies can help you to meet new legal requirements
The German Supply Chain Act (Lieferkettensorgfaltspflichtengesetz, LkSG) has applied since 2023 to companies in Germany with more than 3,000 employees and since 2024 also to companies with more than 1,000 employees. Many of those affected have only slightly dealt with the resulting issues and difficulties so far. Of course, an estimation along the lines of “That doesn’t concern me since I don’t have 1,000 employees” is at least naïve through to negligent, especially so if one is active within the closely intertwined German subsupplier economy, though.
In practice, people who are not directly impacted can thus very quickly become indirectly affected – and the respective consequences of the latter case configuration will hardly be distinguishable from the former one, for consequences will occur irrespectively of the number of the company’s coworkers if clients pass those requirements on through the supply chain.
The purely bureaucratic impacts of the law will still remain to be dealt with, of course even if one leaves out the discussion about whether the law actually makes sense or not. Ultimately, one needs to adjust to the new legal provisions and try to integrate them into daily business life in a manner which is as cost-efficient as possible. Of course, the impacted parties will rarely ever have the chance to implement such new legal requirements for free, though. Therefore, minimizing the efforts and costs while abiding by the existing due diligence obligations in force will constitute the primary goal. The solution can almost inevitably be solely of a digital nature when it comes down to a legal provision which is as far-reaching as the Supply Chain Law and which may affect so many parties.
What is the Supply Chain Law, and what is its underlying intention?
As it has so often been the case before, the Supply Chain Law is actually based on indirect provisions imposed by the United Nations, the UN, which provide for the medium-term implementation of general principles regarding human rights and also environmental standards on the level of national action plans. Primarily, that is about organizing a global economy so as not to unilaterally favor just wealthy states and market players. On the one hand, this is to a great extent about very blurry notions, such as justice, fairness, and participation, but on the other hand, it is also about very clearly defined areas, such as child labor and financial exploitation. Independent monitoring procedures showed that voluntary commitments on the part of the economy and the states did not result in achieving the desired aims there. That is now supposed to be changed by legal provisions.
The basic idea of any and all supply chain laws is to extend the accountability of companies throughout the entire value-added chain. Then, manufacturers are not just accountable for their own actions and processes but also for wrongdoing on the part of subsuppliers and suppliers. Very direct accountability for direct subsuppliers will result from the law. But companies are also accountable for misconduct by direct suppliers they know of.
Especially this two-tiered interpretation is supposed to make sure that a legal provision like the Supply Chain Act shall factually be oriented toward the entire supply chain. So, in the future, one can’t just get out of their accountability for wrongs, ills, and abuses one is aware of anymore by denying any responsibility for them.
Which areas are supposed to be protected under the Supply Chain Law?
First thing, the provisions the Supply Chain Law is based on pertain to rights that protect individual persons, particularly the right to bodily integrity as well as to protection from forced labor, torture, and child labor. Furthermore, general regulations providing for fair wages for workers, the establishment of certain health and safety standards as well as active anti-discrimination measures shall take effect.
On top of that, it is also about abiding by societal standards beyond mere individual rights. Production, manufacturing, and trade are not supposed to deeply interfere with the “rights” of future generations, and thus, they should not waste any important or limited resources. Market players are not supposed to get out of their responsibility anymore by transferring to weaker parties presently unmanageable problems, such as disposal of hazardous waste or illegitimate infringements on nature, environment, and society.
Specific impacts of a supply chain law
Companies with existing and well-functioning quality management systems are not likely to be kept “awake at night” immediately by a new legal provision, such as the Supply Chain Act.
In mere administrative terms, it is just tantamount to an additional risk analysis and risk management branch leading to documentation and reporting requirements deduced from such risk analysis and risk management. But of course, quite a lot of problems will begin to affect companies in practice.
For the main part, the new accountability for entities that are not part of the company is problematic, of course. But resulting issues like heterogenic process and system landscapes will also turn out to be problematic. Ultimately, it is about integrating external processes into the company’s quality management in a manner which is as easy as possible, but efficient at the same time. As the involved parties become “smaller and smaller” toward the bottom of the chain, this will mostly be about looking for the lowest common denominator. Reasonability and adequacy requirements must always be kept in mind, especially when it comes down to small market participants.
Just like with regard to already established quality management systems, practical implementation of the Supply Chain Law is not just aimed at detecting problems but also at remedying them and preventing future difficulties.
Therefore, the focus is supposed to be not just on the detection of ills and abuses but also on specific action to be taken and the introduction of preventative measures in order to avoid similar trouble in the future.
The LkSG provides for fines of up to EUR 8 million or, for companies with an annual turnover of more than EUR 400 million, up to 2% of average global annual turnover; in addition, there is the risk of reputational damage and exclusion from public contracts.
In 2025, the German Federal Government initiated relief measures, including the abolition of the reporting obligation and limiting fines to serious violations. The legal situation in force at any given time is decisive.
At present, it is not clear yet how to delineate the real legal and factual possibilities and to indicate when and where a company has sufficiently fulfilled their due diligence obligations in relative terms.
Implementation of the Supply Chain Act
The specific practical implementation of the Supply Chain Law will definitely constitute a very extensive undertaking again, especially from a consulting perspective. Analyses of existing workflows and systems, risk analyses, and implementation strategies and, last but not least, cooperation and the introduction of joint initiatives together with suppliers will determine major tasks within the impacted companies during the year before the new law comes into effect.
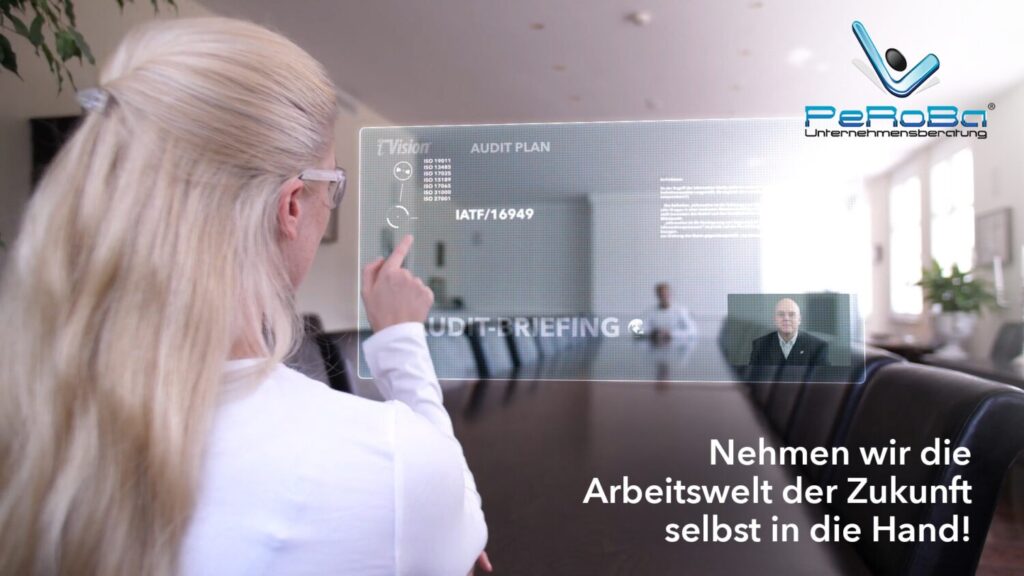
As especially large and global market players will be affected at first, such integration into their own QM systems should not constitute that much of a major job initially. However, matters will become interesting when and where requirements need to be controlled and documented during day-to-day business. Especially since the impacted entities have increasingly been spread out across the globe (for example, manufacturing takes place in the Far East, data processing and support are done in Central Asia…), digital solutions will lend themselves to great tools in this area right away, of course. Remote auditing ranks first with regard to those modern trend topics, such as responsible auditing, and it has ultimately also proven its performance capacity not least during the coronavirus pandemic.
Remote audits within the Supply Chain Law and in the context of corporate social responsibility
With regard to connecting spatially spread out entities on more than audio-visual levels as efficiently as possible, remote auditing has proven to be a resilient and robust solution during the pandemic years.
Remote audits connect digital communication options (video / audio conferences) in a targeted manner to teamwork and quality management elements. The focus is always especially on automated documentation and reporting for simplifying or rendering obsolete follow-up processes. Therefore, it stands to reason why remote auditing technologies can be considered suitable solutions for practical problems emerging in the wake of the Supply Chain Act all the way up to unannounced audits / inspections in order to make sure that requirements are being met.
Its software-driven approach is also part of the advantages of remote audits. The necessary hardware (PCs, laptops, tablet computers, and smartphones) is used everywhere on the planet. The required net infrastructure varies, to be sure, in terms of quality, but coverage is also very comprehensive in most areas here. So, only higher-value services based on data glasses would have to be initiated in a completely new way. The services that can possibly be utilized depend primarily on the used software platforms and may also be extended at will if needed. The “factual possibilities” and limits of due diligence obligations addressed briefly earlier on can evidently be expanded to an extreme extent over this.
But of course, its economic aspects are likewise among the advantages of remote auditing. Whereas initial and introductory costs may be very high, depending on specific cases, the savings resulting from remote auditing later on will be permanent and often times also steadily increasing. Above all, the end of unnecessary traveling activities and of the accompanying time efforts and staff expenditures can, in practice, lead to very fast amortization of investments. But there are also positive aspects from a mere quality perspective. Due to fewer coordination efforts and decreasing costs, communication and control can take place much more frequently and, if needed, also in a much more unannounced manner than previously.
But specific remote auditing solutions for support with the requirements of the Supply Chain Law must ultimately have some important characteristics. First and foremost, these include scalability and the ability to integrate them into existing system and process landscapes. Since the requirements of the Supply Chain Law on quality management are ultimately not completely new, individual developments should be exceptions rather than the rule, and proven modular solutions ought to be relied on.
We will be happy to advise you on how our excellent iVision platform for remote auditing can also support you in meeting your requirements based on the future challenges of the Supply Chain Law and in implementing them in a targeted and purposeful manner. Feel free to get in touch and ask us right away.
Frequently asked questions about remote audits
What is a remote audit?
In a remote audit, the auditor is not physically present at the audit location; technical aids are used instead. The auditor and the organisational unit being audited are usually connected via audio and video applications, through which the audit is managed and documented.
What types of remote audits are there?
In practice, a distinction is made between fully remote, partly remote and follow-up remote audits, depending on which audit stages the auditor attends on site. Fully remote audits are still the exception. Remote audits have proven particularly successful for audit follow-up actions, where the auditor’s physical presence is usually not necessary.
What are the advantages of remote auditing?
Remote audits actively reduce costs – above all travel and accommodation costs – with obvious environmental and climate benefits. Once fully set up, they also save time quickly, especially with high audit frequencies or a large audit overhead.
Aren’t remote audits too inflexible?
It is very difficult to exploit all the advantages with standard software alone. What is needed is dedicated remote audit software that can be adapted modularly to different needs (standards, sectors, markets). iVision® Remote Audit is one of these advanced solutions.
About PeRoBa®:
PeRoBa® Unternehmensberatung GmbH has specialised in management systems since 1991. The company has been headquartered in Baldham since 2011 and also maintains an office on Prinzregentenstraße in Munich. PeRoBa® advises, audits and assesses to support clients in introducing and implementing their management systems, and also offers audits, QM training, seminars and workshops. Since January 2016, the in-house, patented software iVision® – Smart Remote Audit Solution has been on the market.
Dr. Roland Scherb is the founder and Managing Director of PeRoBa® Unternehmensberatung GmbH, certified to DIN EN ISO 9001, ISO 14001 and ISO 27001 and based in Baldham. He is President of the Bundesverband der Auditoren e. V. (German Federal Association of Auditors), head of the ISO Certification Competence Forum at BVMW e. V. (German Association for Small and Medium-sized Businesses) and a member of the DIN working committee NQSZ NA 147-00-07 GA on the revision of DIN EN ISO 19011. He is also a book author as well as a trainer and lecturer at renowned educational institutions on management systems and the associated core methods.
How may we help you?
Arrange a free, no-obligation initial consultation via online appointment, or send us a message using our contact form. You are also welcome to call us.
In the free initial consultation, we first clarify your needs.